Author: The IndiaPay Team

  • The ₹2 Coin That Bought an iPhone: What Indian Comedy Tells Us About Money

    The ₹2 Coin That Bought an iPhone: What Indian Comedy Tells Us About Money

    The Sketch That Broke the Internet (or at Least Indian YouTube)

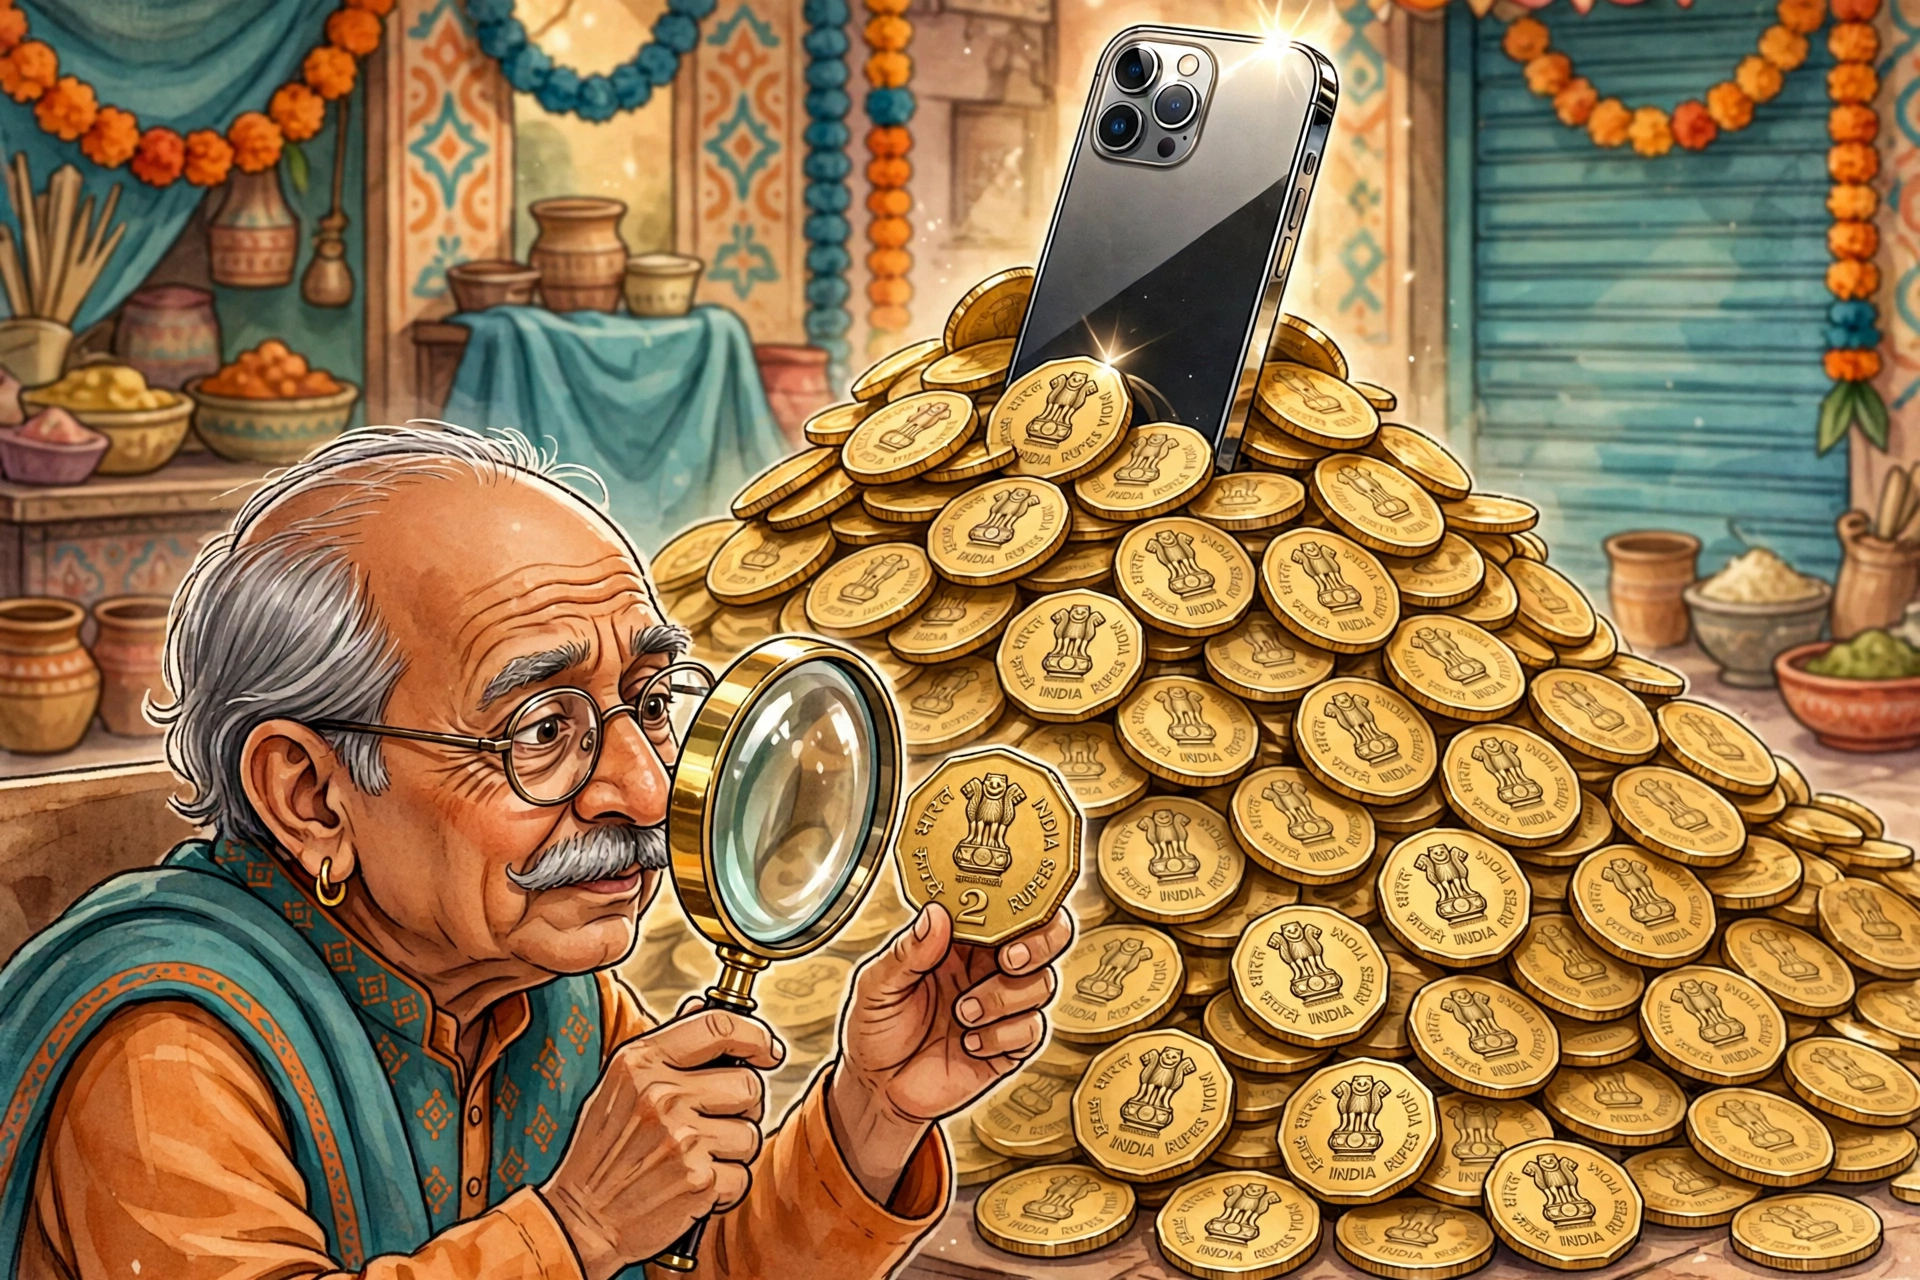
    Thirty-five million views. Six hundred ninety-four thousand likes. For a short comedy sketch with a premise a five-year-old would reject as unrealistic: buying an iPhone 18 Pro Max with ₹2 coins.

    It is, on its face, absurd. An iPhone costs over a lakh rupees. You would need roughly fifty thousand ₹2 coins. They would weigh about 250 kilograms. You would need a truck, not a wallet.

    And yet 35 million people watched it. They laughed. They shared it. They tagged their cousins.

    Why does this specific joke land so hard in India? The answer tells you more about Indian money psychology than any economics textbook. And buried inside the laughter is a question worth real money: are any of those old coins in your grandmother’s steel almirah actually worth something?

    Let us start with the funny part. Then we will get to the part that could pay for your next flight to India.

    The Uncle Who Checks Every Coin

    Every Indian family has one. The uncle who, upon receiving change at a shop, holds each coin up to the light like a jeweler appraising a diamond. Who has opinions about which year’s ₹5 coin “feels heavier.” Who once read a WhatsApp forward claiming a particular ₹1 coin was worth ₹5 lakh and has been checking ever since.

    This uncle is not crazy. He is the product of a very specific national experience with money.

    Consider what the average Indian over forty has lived through. In 2016, the government announced on live television, with four hours’ notice, that all ₹500 and ₹1,000 notes would cease to be legal tender by midnight. People stood in bank queues for weeks. Weddings were postponed because families could not access cash. The notes you had in your wallet that morning were, by evening, colorful paper.

    Now: was demonetization good policy or bad? Economists are still arguing, and this is not that article. But the psychological effect is not debatable. An entire nation learned, in one evening, that money is a story the government tells, and the government can change the story whenever it wants.

    Coins, though. Coins survived. Nobody demonetized the ₹2 coin. And so the coin became, in the Indian imagination, the honest money. The money that cannot be cancelled by a press conference. The sketch about buying an iPhone with ₹2 coins is funny precisely because it inverts the trauma: what if the smallest, most ignored denomination turned out to be the most powerful?

    The WhatsApp Forward Economy

    If you are Indian and over thirty, you have received this forward. It arrives from a relative, usually with several exclamation marks:

    “RARE ₹1 COIN FROM 1985 WORTH ₹5 LAKH!!! CHECK YOUR OLD COINS!!!”

    Below it: a blurry photo of a coin. Sometimes the photo is of a completely different coin than the one described. Nobody checks. The forward travels through seventeen family groups before lunch.

    Here is the thing: the forward is not entirely wrong. It is wrong the way a stopped clock is right twice a day. Most old ₹1 coins are worth exactly ₹1. But a tiny number of them (specific minting years, mint marks, or errors) genuinely are worth lakhs.

    The WhatsApp forward economy runs on a one percent truth stretched over ninety-nine percent fantasy. That one percent is real, though: the difference between the ₹1 coin in your pocket and the ₹1 coin worth ₹1.5 lakh is knowledge most people do not have.

    Which Old Indian Coins Are Actually Worth Money

    Forwards aside, here is what Indian collectors and auction houses actually pay for:

    The British India Coins (Pre-1947)

    This is where the serious money lives. Coins minted under British rule, especially in silver, are the blue-chip stocks of Indian numismatics.

    The most famous is the 1911 one-rupee coin, sometimes called the “pig coin” because a minting quirk made the elephant on the reverse look porcine. In uncirculated condition, these have sold for ₹3 lakh to ₹15 lakh at auction. The value comes from a specific variety: the 1911 rupee without a dot below the date, a tiny minting variation that most people would never notice.

    Other British India coins with real market value include the 1939 one-rupee coin (wartime silver issue), the 1862 Victoria rupee in rare varieties, and proof sets from the Bombay and Calcutta mints. Silver content gives these a floor; collector demand pushes the ceiling far higher.

    Early Republic Coins (1950s to 1970s)

    After independence, India minted coins in cupronickel featuring the Ashoka Lion Capital. Most are common. But low-mintage years and proof-only issues are genuinely scarce.

    The 1970 proof one-rupee coin from the Mumbai mint has traded around ₹2.25 lakh. The 1985 Kolkata mint circulation rupee, an ordinary-looking coin, has sold for over ₹1.3 lakh because of an unusually small mintage that year. These are the coins most likely to be hiding in that steel almirah: ordinary-looking, easily overlooked, genuinely valuable.

    Error Coins (Any Era)

    Minting mistakes are the lottery tickets of coin collecting. Off-center strikes, double dies, wrong-planchet strikes, rotated dies: these turn a ₹5 coin into something worth ₹50,000 or more.

    A wrong-planchet error (a coin struck on another denomination’s blank) can fetch ₹1 lakh to ₹3 lakh. Major mismatched-die errors have crossed ₹3 lakh. The catch: you need to know what you are looking at. Most “error coins” people find are just damaged coins, worth nothing extra.

    Commemorative Coins

    India has issued commemorative coins for events and personalities: the 100-rupee Indira Gandhi coin, the 150-rupee Tagore coin, the 500-rupee Gandhi Smriti coin. Uncirculated proof sets trade between ₹25,000 and ₹1 lakh. Not retirement money, but real value sitting in drawers across the country.

    What Is NOT Worth Money

    Let us be blunt, because the forwards will not be: your regular stainless steel ₹1, ₹2, or ₹5 coins from recent years are worth face value. Full stop. The ₹2 coin from the comedy sketch, the one that supposedly buys an iPhone, is worth ₹2. The joke is funny because it is impossible.

    Modern Indian circulation coins are minted in the hundreds of millions. Scarcity is what creates value, and there is nothing scarce about them. If someone on Facebook Marketplace offers to buy your 2019 ₹5 coin for ₹50,000, that person is running a scam, not a coin dealership.

    How to Check What You Have

    So your grandmother does have that almirah. Or your parents have a box. Or you do. Here is how to evaluate what is inside without falling for the forwards:

    Step 1: Sort by year. Anything pre-1980 deserves a closer look. Anything pre-1947 deserves a very close look. Modern stainless steel coins can go back in the jar.

    Step 2: Check the mint mark. Below the year: a small dot means Noida, a diamond means Mumbai, a star means Hyderabad, no mark means Kolkata. Certain mint-year combinations are scarcer than others, and missing or defective mint marks can themselves indicate a valuable error.

    Step 3: Look at the metal. If it is heavy for its size with a silvery ring when tapped, it might be silver or cupronickel rather than stainless steel. That alone does not make it valuable, but it puts it in the category worth researching.

    Step 4: Check for errors. Is the design off-center? Is there doubling visible in the lettering? Does one side look like it belongs to a different coin? Photograph anything unusual and compare against known error types before getting excited.

    Step 5: Get a real appraisal. Do not trust the WhatsApp forward. Do not trust the Facebook buyer who DMs you within minutes of posting. Legitimate options: auction houses like Marudhar Arts and Todywalla Auctions, the major coin exhibitions in Mumbai and Chennai, and certified dealers affiliated with the Indian Coin Society. For high-value pieces, international grading services like NGC or PCGS will authenticate and grade the coin, which dramatically increases buyer confidence and sale price.

    The NRI Angle: The Almirah Arbitrage

    Here is where it gets interesting for the NRI reader.

    Millions of NRI families live this exact situation: parents or grandparents in India sitting on boxes of old coins, nobody knowing what is valuable, and you, reading this from New Jersey or Seattle, the one most likely to actually research it.

    There is a genuine, small-scale arbitrage here. Not “get rich” arbitrage. “Pay for the Diwali flight” arbitrage. A single 1985 Kolkata rupee in good condition, sitting in a steel box in Pune, is worth more than a round-trip ticket.

    The play: next time you visit, spend an afternoon with the coin box. Sort by the steps above. Photograph anything pre-1980. Send the photos to a reputable dealer for a preliminary opinion before you fly home. If something looks promising, carry it back properly (legalities below) or consign it to an Indian auction house.

    The Legal Fine Print (Because This Is India)

    Coin trading in India has some real boundaries:

    Most old coins are legal to buy and sell freely. The restrictions kick in for ancient coins: items over 100 years old with archaeological significance may require permissions under the Antiquities and Art Treasures Act. You cannot export notified antiquities without a license. In practice, this affects Mughal-era and earlier pieces, not your grandfather’s 1970s rupees.

    For NRIs specifically: carrying old coins out of India in personal baggage for a legitimate collection is generally fine for ordinary numismatic items. For anything potentially qualifying as an antiquity, check with the Archaeological Survey of India before you pack it. When in doubt, sell through an Indian auction house and repatriate the proceeds through normal banking channels, which avoids the question entirely.

    This is not legal advice. For high-value pieces, talk to a professional. But for the overwhelming majority of what is sitting in family almirahs, the legal situation is straightforward: it is yours, you can sell it.

    Why the Sketch Got 35 Million Views

    Let us come back to where we started. A comedian pretends to buy an iPhone with ₹2 coins. Thirty-five million people watch.

    It works because it touches three live wires in the Indian psyche at once. First, the fantasy of hidden value: the deep, almost religious belief that something worthless-looking might secretly be precious. This is the same belief that powers the WhatsApp forwards, the uncle checking mint marks, the grandmother who will not throw away a single coin.

    Second, the demonetization scar. A nation that watched its currency die on live television has a complicated relationship with the idea of what money is “really” worth. The sketch is, underneath the slapstick, a revenge fantasy: the little coin, the one nobody demonetized, the one the government forgot about, turns out to be the most powerful money of all.

    Third, and simplest: it is just funny. The image of someone solemnly counting out fifty thousand coins at an Apple store is objectively hilarious. Comedy does not always need a thesis. Sometimes a truck full of ₹2 coins is just a truck full of ₹2 coins.

    But the best comedy has a thesis anyway, whether the comedian intended it or not. This one does. It is about what Indians believe about money: that value hides in unexpected places, that the official story is not the whole story, and that the humble ₹2 coin, overlooked by everyone, might just be the most honest money in the country.

    Now go check the almirah. You probably will not find ₹15 lakh. But you might find something worth a very nice dinner. And you will definitely find a story.


    Smarter money moves, with a sense of humor

    One email a week on NRI money, investing, and the cultural chaos in between. Funny first, useful always.

    Disclosure: IndiaPay may earn a commission from links on this page.
  • Before Apps: How NRIs Sent Money Home in the 1990s

    Before Apps: How NRIs Sent Money Home in the 1990s

    The Three-Week Wait

    In 1994, if you lived in New Jersey and wanted to send $500 to your parents in Kochi, here is what you did:

    You went to your bank. You filled out a paper form. You paid a fee that nobody could quite explain. The bank issued a demand draft, a physical piece of paper promising payment, which you mailed to India by international post. Your parents received it in two to three weeks, took it to their bank, and waited another week for it to clear.

    Total elapsed time: roughly a month. Total cost: somewhere between 5% and 10% once you added up the fees, the terrible exchange rate, and the postage. Total transparency: zero. For most of that month, your $500 existed only as a rumor.

    This was not the backward option. This was the normal option.

    The Menu of Bad Options

    The 1990s NRI had roughly four ways to move money, and each was bad in its own special way:

    Method How it worked Speed Cost The catch
    Demand draft Bank-issued paper draft, mailed internationally 3-5 weeks door to door 5-10% all-in Could be lost, stolen, or delayed by the postal service of two countries
    Telegraphic transfer (TT) Bank-to-bank wire via SWIFT/telex 3-7 days $25-45 flat fee + 2-4% rate markup Only worth it for large amounts; paperwork at both ends
    Carried cash The uncle with dollars in his socks Next flight home 0% (plus risk) Customs limits, theft risk, and the exchange happened at whatever rate the local money changer offered
    Hawala Trust-based informal network Hours to days 1-2% Illegal in most jurisdictions; no recourse if the operator vanished

    Read that table again. The illegal option was the fastest and cheapest. That tells you everything about how badly the formal system served migrants in the 1990s.

    Why It Was So Bad: The 1991 Context

    To understand 1990s remittances, you have to understand 1991. India went through a balance-of-payments crisis so severe that the government airlifted 67 tonnes of gold to London as collateral for emergency loans. Foreign exchange reserves had fallen to roughly $1 billion, barely three weeks of imports.

    The reforms that followed gradually opened the capital account and made the rupee more flexible after 1993, but the plumbing of cross-border money movement stayed Victorian for another decade. As recently as 2003, 86% of all non-cash payments in India were still paper instruments: cheques, demand drafts, cash. Electronic payments were a rounding error.

    In 1990, India received just $2.38 billion in remittances and ranked 8th in the world. By 1995, it was number one at $6.2 billion. By 2000: $12.9 billion. By 2010: $53.5 billion. In FY25: $135.4 billion. The World Bank data shows India has topped the global remittance table for 23 of the 27 years since 1995.

    The money did not just grow. The pipes changed completely.

    The NRI Lens: What It Felt Like

    Ask any NRI who moved abroad before 2000, and the remittance stories come out like war stories.

    There is the story of the demand draft that arrived after the medical emergency it was meant to cover. The story of the telegraphic transfer where the bank “lost” the SWIFT message for eleven days. The story of timing a trip home around carrying the maximum legal cash, and the specific anxiety of the customs line at Mumbai airport.

    But there is also something the old-timers describe that the app generation does not have: the ritual weight of it. Sending money in 1995 was an event. You went to the bank. You stood in line. You filled out forms in triplicate. You called home to say “I sent it, it should reach by the end of the month.” The slowness created a ceremony around the act. Today’s instant transfer is efficient, but nobody calls home to announce a Wise transfer the way they announced a demand draft.

    Speed ate the ritual. Whether that is a loss or a liberation depends on how old you are.

    The India Lens: What the Family Experienced

    From the receiving side, the 1990s system had a peculiar feature: the delay was a budgeting tool. Families knew the money was coming “sometime next month,” and planned around the uncertainty. The arrival of the draft was an occasion. Neighbors knew. The bank manager knew.

    Compare that to today, when $500 lands via IMPS in four minutes and nobody marks the occasion. The emotional bandwidth of remittances has collapsed even as the financial bandwidth exploded. Your parents in 1995 felt each transfer. Your parents in 2026 get a push notification.

    The old system’s slowness also protected people from themselves. You could not panic-send money at 2 AM because the rupee moved. You could not check the rate twelve times a day. The friction was a feature, accidentally.

    The Great Inversion

    Now, the reframe on today’s fees:

    The global average cost of sending remittances is 6.36% (World Bank, Q3 2025), still more than double the UN’s 3% target. Banks charge nearly 15%. The fintech apps charge 1% or less. NRIs complain, rightly, that even 1% is too much.

    But the 1990s NRI paid 5 to 10% and waited a month. The hawala user paid 1 to 2% and broke the law. Today’s “expensive” legal option is cheaper than the 1990s illegal option, and it arrives in minutes.

    The real revolution was not speed. It was legitimacy at low cost. For the first time in history, an ordinary migrant can move money across the world cheaply, quickly, and entirely within the law. Every generation before this one had to choose two of the three.

    The Thought Provocation

    Nostalgia for the demand-draft era is misplaced, but it contains a real insight: friction made money meaningful. The month-long wait, the trip to the bank, the phone call announcing “I sent it”, these turned a financial transaction into an act of care with weight and ceremony.

    Today’s system optimized away the wait, the cost, and the ceremony all at once. The money moves perfectly. But something was lost when sending $2,000 home became no more momentous than ordering groceries. The apps solved the economics of remittances completely, and accidentally deleted the meaning of remittances.

    Maybe the next revolution in money movement will not be about making it faster or cheaper. Maybe it will be about making it matter again. The uncle with cash in his socks was inefficient, risky, and illegal. He was also, in some way the apps have not figured out, present.


    The NRI money playbook, one email a week

    Remittance tricks, NRE/NRO guides, tax deadlines, and investment rules for Indians abroad. Practical, numbers-first, no fluff.

    Financial disclaimer: This is a historical and educational piece, not financial advice. Sources: World Bank remittance data via The Hindu BusinessLine analysis (1990-2021 rankings); RBI payment system data (86% paper instruments in 2003); World Bank Q3 2025 remittance cost data (6.36% global average); Economic Survey of India 2025-26.

  • The H1B Worker’s First Paycheck: Where Does the Money Go?

    The H1B Worker’s First Paycheck: Where Does the Money Go?

    Month One

    Rohan landed in Seattle on a Tuesday in October. By Friday he had a Social Security number, a studio apartment with a mattress on the floor, and a job offer letter that said a number he had rehearsed saying out loud in the mirror: $135,000 a year.

    He did the math on the flight over. $135,000 divided by 12 is $11,250 a month. In rupees, at roughly 90 to the dollar, that was over Rs. 10 lakh. Per month. His father, a retired bank manager in Pune, had earned Rs. 85,000 a month at his peak.

    Rohan felt, for approximately six days, like the richest person he knew.

    The First Paycheck Arrives

    The direct deposit hit on the 15th: $7,842.

    Not $11,250. $7,842.

    Rohan stared at the pay stub the way you stare at a restaurant bill that has items you did not order. Federal income tax. State income tax (Washington has none, a fact he would later cite the way people cite scripture). Social Security. Medicare. Health insurance premium. 401(k) contribution, which someone in orientation had strongly suggested and he had accepted the way you accept a seatbelt on a plane.

    Nearly a third of the salary, gone before it touched his account. Nobody on the flight over had mentioned this part.

    The Rent Conversation

    The studio was $1,850 a month. Utilities, $140. A bus pass, $100. Groceries, which he optimistically budgeted at $300 and which came in at $480 because American vegetables are priced like they were flown in by private jet (some of them were).

    Phone plan: $45. Renter’s insurance: $18. The mattress fund: ongoing.

    Running total of non-negotiables: roughly $2,800. Remaining from the paycheck: about $5,000.

    Then his mother called.

    The Call

    It was not a demanding call. It was worse. It was a not-demanding call.

    “Beta, don’t worry about us, we are fine. Your father and I were just talking, the fixed deposit matured, we were thinking of renewing it. But don’t send anything, you just reached, settle down first.”

    Rohan, who had been waiting his entire adult life for the moment he could send money home, heard this as: send money home immediately.

    He opened his laptop and typed “send money to India” into Google.

    The Fee Education

    What followed was the classic NRI onboarding sequence, compressed into one evening:

    Step 1: The bank. His US bank would wire the money for $45 plus an exchange rate that was, he later learned, roughly 3% worse than the real rate. On $2,000, that was about $105 in total cost. He closed the tab.

    Step 2: The apps. Wise, Remitly, Xoom, each with a different definition of “free.” He learned the central lesson of remittances within an hour: the fee is not the price. The exchange rate is the price. A $0 fee with a bad rate costs more than a $7 fee with a good rate.

    Step 3: The account question. Where should the money land? His parents’ regular savings account? His own NRE account? He did not know what NRE meant yet. He would learn, the way everyone learns, from a slightly panicked phone call with a cousin who had been in the US for six years.

    He sent $2,000 through an app. It arrived the next morning. His mother called to say it came. She did not mention the amount. She mentioned that it came fast.

    Where the Money Actually Went

    Here is Rohan’s first full month, reconstructed:

    Amount Share of gross
    Gross monthly pay $11,250 100%
    Federal + payroll taxes ~$2,400 ~21%
    Health insurance + 401(k) ~$1,000 ~9%
    Take-home pay ~$7,850 ~70%
    Rent + utilities + basics ~$2,800 ~25%
    Transfer to India $2,000 ~18%
    Transfer fee + rate cost ~$12 ~0.1%
    Remaining (savings, life) ~$3,000 ~27%

    Of the $11,250 he “earned,” about $2,000 reached his parents. That is 18%. The single biggest destination of his salary was not his family, not his landlord, not his savings. It was taxes.

    This is the part nobody tells you at the visa interview.

    The NRI Lens: What Rohan Did Not Know Yet

    Rohan’s story is a composite, but every detail in it is true for thousands of new H1B workers each year. Indians receive about 71% of all US H-1B visas; the US sends over $100 billion a year in outbound remittances, a large share of it flowing to India: $135.4 billion in FY25, the most of any country on earth.

    What Rohan did not know in month one, and what every new arrival learns within a year:

    The transfer is the easy part. The hard part is everything around it: which account the money lands in (NRE vs NRO changes the tax treatment completely), whether the transfer is a gift or support (it matters for US gift tax thresholds), and what happens to the money after it arrives (sitting in a savings account at 3% vs an NRE fixed deposit at 7%).

    The fee is the smallest line item. Rohan spent an evening agonizing over a $12 transfer cost. He spent zero evenings thinking about the $2,400 in taxes, which is the actual story of his paycheck. The remittance industry has brilliantly convinced NRIs that the fee is the thing to optimize, while the tax code quietly takes twenty times more.

    The guilt is the real tax. No financial product addresses this, but it is the largest force in NRI money movement: the feeling that you should send more, the mother’s “don’t worry about us,” the mental accounting where every dollar spent on yourself in America is a dollar not sent to Pune. Rohan’s $2,000 was not a financial decision. It was an emotional one wearing a financial costume.

    The India Lens: What the Family Sees

    From Pune, the story looks completely different. Rohan’s parents do not see the pay stub. They see a son who earns “Rs. 10 lakh a month” and sends Rs. 1.8 lakh home. The math they do is simple: he keeps 80%.

    This asymmetry, the family seeing gross while the worker lives net, is the source of half the tension in NRI families. The parents are not wrong; they just have different numbers. The worker is not ungrateful; they just have different bills. Nobody lies. Everyone misunderstands.

    The families, meanwhile, have their own onboarding: learning that the money arrives via IMPS in minutes now (not the demand draft that took three weeks in the 1990s), learning not to ask “but the rate was better yesterday,” learning that “I will send it on the 1st” is a promise the US payroll system does not always keep.

    The Thought Provocation

    Rohan’s first paycheck teaches the lesson that no remittance comparison article can: sending money home is not a transaction. It is the moment an immigrant’s financial life splits in two.

    From that first transfer onward, Rohan does not have one financial life. He has two, running in parallel, in different currencies, under different tax codes, serving different obligations. The $12 fee is trivia. The real story is that he is now a person who earns in dollars, owes in dollars, saves in dollars, and loves in rupees.

    Every NRI knows this split. Nobody talks about it at parties. But it is the defining financial fact of the diaspora: you do not just move countries. You move money systems. And the first paycheck is when you find out how much of yourself you left in each one.


    The NRI money playbook, one email a week

    Remittance tricks, NRE/NRO guides, tax deadlines, and investment rules for Indians abroad. Practical, numbers-first, no fluff.

    Rohan is a composite character drawn from common H1B experiences; tax figures are illustrative for a single filer at this income level and vary by state and situation. Sources: Economic Survey of India 2025-26 (India $135.4B remittances FY25); IOM World Migration Report 2026 (US outbound remittances); USCIS H-1B data on Indian nationals’ share.

  • Wise vs Remitly vs Xoom: The 2026 Fee Shootout for India Transfers

    Wise vs Remitly vs Xoom: The 2026 Fee Shootout for India Transfers

    The $312 Question

    Meet two NRIs. Both live in Seattle. Both send $2,000 home to Bangalore every month. One uses Wise. The other has used Xoom since 2019 because “it just works.”

    After one year, the Xoom loyalist has sent $312 less to his family than the Wise user. Same dollars out of the paycheck. Same intention. The only difference is the app.

    That is the cost of provider loyalty in remittances: small, invisible, compounding. Most NRIs pick one provider and never re-check. This article is the re-check: Wise, Remitly, and Xoom head to head.

    How Each Provider Actually Makes Money

    Before the numbers, a note on the pricing model: each provider hides its profit in a different place:

    Provider How they charge you Where the real cost lives
    Wise Upfront percentage fee (roughly 0.4% to 1.5% depending on amount and payment method) In the visible fee. The exchange rate is the real mid-market rate with no markup, so what you see is what you pay.
    Remitly Flat fee ($0 to $3.99; typically $0 on transfers over $1,000) In the exchange rate. The fee looks tiny or free, but the rate includes a markup over the mid-market rate. This is the classic “free transfer” illusion.
    Xoom (PayPal) Variable fee ($0 to ~$4.99 on bank-funded transfers; much higher on cards) In both. Xoom charges a fee AND applies an exchange-rate markup. It is usually the most expensive of the three for bank-funded transfers.

    The golden rule: always compare the final rupee amount delivered, not the fee. A “$0 fee” transfer with a bad rate costs more than a $7 fee with a great rate.

    The Shootout: $1,000 Transfer

    On a $1,000 bank-funded (ACH) transfer, the 2026 pattern looks like this:

    Wise Remitly Xoom
    Fee ~$7 (varies by payment method) $3.99 (Economy) or $0 over $1,000 ~$2.99 to $4.99 (bank-funded)
    Exchange rate Mid-market, no markup Below mid-market (markup) Below mid-market (markup)
    Speed Minutes to 2 days Minutes (Express) or 3-5 days (Economy) Minutes for most bank/UPI transfers
    Payout options Bank deposit only Bank, UPI, cash pickup, mobile wallet Bank, UPI, cash pickup, mobile wallet
    Typical winner Most rupees delivered Fastest, competitive on promos Convenience for PayPal users

    The short answer for $1,000: Wise usually delivers the most rupees because the mid-market rate beats the competitors’ markups by more than their fee difference. Remitly can win for first-time users thanks to promotional rates. Xoom rarely wins on price, but wins on convenience if you already live inside PayPal.

    The Shootout: $10,000 Transfer

    This is where the math changes with size. Remitly published its own head-to-head test against Wise in September 2026 across amounts from $1,000 to $300,000, worth knowing even allowing for the source: at every amount tested, Remitly’s $0 fee delivered more total rupees than Wise once Wise’s percentage fee was included, and the gap widened as amounts grew. At $300,000, the difference was over Rs. 37,000.

    That does not make Remitly the automatic winner. The point: the “best” provider depends on the amount. Wise’s fee grows with the transfer; Remitly’s stays flat at zero while its rate markup stays roughly proportional. For very large transfers, a flat-fee-plus-markup model can beat a percentage-fee model. For small transfers, the reverse.

    Xoom, meanwhile, charges both a fee and a markup at every tier, which is why it consistently finishes third on pure cost. Its case is convenience, not price.

    The NRI Lens: It Is Not Just About the Transfer

    Here is what the fee comparisons never tell you. The transfer is one decision inside a bigger system:

    Which account receives the money? If it lands in your NRE account, the interest is tax-free in India and repatriation is unlimited. If it lands in an NRO account, interest faces 30% TDS and repatriation is capped at $1 million per year with 15CA/15CB paperwork. The “cheapest” transfer into the wrong account can cost you more in a year than a decade of fee differences. (Our Wise vs Remitly deep dive covers the NRE/NRO decision in full.)

    The US remittance tax. As of early 2026, the US applies a 3.5% tax on formal remittance transfers, deducted by the provider before funds move. That means a $1,000 transfer now costs you about $1,036 out of pocket regardless of provider. Factor it into your math, and keep records: dates, amounts, provider details.

    Speed has a price. Remitly’s Express (minutes) costs more than its Economy (3 to 5 days). Xoom is typically instant. Wise ranges from minutes to 2 days. If the money is for a property down payment with a deadline, speed matters more than $5. If it is monthly family support, Economy pricing wins every time.

    The India Lens: What Happens on Arrival

    From the receiving side, the mechanics are refreshingly boring in 2026: money arrives via IMPS or NEFT into any Indian bank account, usually within minutes for the fast options. UPI delivery is available through Remitly and Xoom. Cash pickup still matters for families in areas with thin banking access, which is the one place Xoom and Remitly beat Wise (Wise does bank deposits only).

    Practical note: transfers above Rs. 5 lakh can take longer (up to 2 hours instead of minutes on Xoom), and sending during Indian banking hours (9:30 AM to 4:30 PM IST) speeds things up. Weekend transfers on either side slow everything down.

    The Honest Verdict

    If you are… Use… Why
    Sending $500 to $5,000 monthly Wise Mid-market rate usually wins at this size; transparent pricing
    Sending $10,000+ occasionally Compare Wise vs Remitly live Flat-fee models can win at size; run both quotes before sending
    New to remittances Remitly First-transfer promotional rates are genuinely the cheapest entry point
    Already deep in PayPal Xoom Convenience; accept you are paying a premium for it
    Need cash pickup for family Remitly or Xoom Wise does not offer it

    And the one rule that beats all of the above: re-check once a year. Providers change pricing. Promos expire. The app you picked in 2019 is not necessarily the cheapest in 2026. Ten minutes of comparison shopping per year is the highest-paid ten minutes in personal finance.

    The Thought Provocation

    Here is the uncomfortable truth this comparison leads to: the remittance industry profits from your loyalty, not your satisfaction. Every provider’s pricing is designed to feel fine on any single transfer while quietly taxing the habit of never comparing. The fee is not the product. Your inattention is the product.

    India received over $150 billion in remittances in 2025, the most of any country on earth, according to World Bank and IFAD data. The global average cost of sending money is still 6.36%, more than double the UN’s 3% target. Every fraction of a percent you save is money that stays with your family instead of a payments company. That is worth ten minutes a year.

    Fine Print

    Fees and exchange rates change constantly; the figures above reflect published ranges and third-party comparisons as of late 2026. Always run a live quote in each app before sending. This article compares providers on cost and features, not on investment advice. Remittance tax rules (US and India) change; verify current regulations before large transfers. FEMA/RBI rules apply to how received funds are held and repatriated.

    Financial disclaimer: This article is for educational purposes and does not constitute financial advice. Exchange rates, fees, and tax rules change frequently. Verify all figures with the provider at the time of transfer and consult a qualified professional for tax matters.


    The NRI money playbook, one email a week

    Remittance tricks, NRE/NRO guides, tax deadlines, and investment rules for Indians abroad. Practical, numbers-first, no fluff.

    Disclosure: IndiaPay may earn a commission from links on this page.
    Sources: World Bank Migration and Development data via IFAD Sending Money Home 2026 report (India $150.7B remittances in 2025; global average cost 6.36%); Remitly’s published Wise comparison (September 2026); provider fee pages for Wise, Remitly, and Xoom; Economic Survey of India 2025-26.

  • How to Send Money to India from the USA: The NRI’s Complete 2026 Guide

    How to Send Money to India from the USA: The NRI’s Complete 2026 Guide

    The NRI’s dilemma: it is not just about the cheapest transfer

    You are Priya, a software engineer in Austin on an H1B. Every month you send $2,500 home: $1,500 for your parents, $1,000 you are saving toward a flat in Hyderabad. You have three browser tabs open comparing Wise, Remitly, and your bank. You pick the cheapest. Done, right?

    Not quite. Because the transfer is only the first of four decisions, and most guides stop at decision one. The four decisions are: which service, which Indian account receives it, what happens to the money after it lands, and how the tax authorities on both sides see it. Get the first right and the other three wrong, and you have saved $6 on the transfer while losing hundreds on the back end.

    This guide covers all four.

    How money transfers to India actually work

    Every transfer has the same two cost components, no matter which service you use:

    1. The transfer fee. A flat fee, a percentage, or both. This is the number companies advertise.
    2. The exchange rate margin. The difference between the mid-market rate (the “real” rate you see on Google) and the rate the company gives you. This is where most of the cost hides.

    A service advertising “$0 fees” can still cost you 2 to 3 percent if their exchange rate is marked up. A service charging a $5 fee with the real exchange rate can be far cheaper. Always judge a transfer by the final rupee amount, not the advertised fee.

    There is a third cost most guides ignore: the opportunity cost of the receiving account. Money landing in the wrong account type can cost more in tax and lost repatriation rights than any transfer fee. We cover that in the NRE/NRO section below.

    Method 1: Specialist transfer apps (recommended for most people)

    Companies like Wise, Remitly, and Instarem exist for one purpose: moving money across borders cheaply. They consistently beat banks because international transfers are their entire business, not a side product.

    Typical cost: 0.5% to 1.5% all-in for USD to INR. (Verify live; corridors shift.)
    Typical speed: Hours to 1 business day.
    Best for: Regular transfers of $200 to $50,000.

    How it works: create an account, verify your identity, enter the amount and your recipient’s Indian bank details, pay with your US bank account or debit card. The company handles conversion and delivery.

    Try Wise | Try Remitly | Try Instarem

    Our detailed comparisons:

    Method 2: Xoom (PayPal’s transfer service)

    Xoom is PayPal’s international transfer brand. Fast and convenient, especially with an existing PayPal account, but rarely the cheapest.

    Typical cost: Higher than Wise or Remitly on most amounts, due to exchange rate margin. (Verify live.)
    Typical speed: Minutes to hours.
    Best for: PayPal users who value convenience, urgent transfers, cash pickup needs.

    Xoom supports bank deposit, UPI, and cash pickup across India, a wider payout network than most specialist apps. If your recipient needs cash rather than a bank deposit, Xoom is worth comparing.

    Method 3: Western Union and MoneyGram

    The legacy players. Thousands of agent locations, decades of brand recognition, usually the highest total cost.

    Typical cost: 2% to 5% all-in once you include the rate margin. (Verify live.)
    Typical speed: Minutes (in person) to 1 day (online).
    Best for: Cash-to-cash transfers, recipients without bank accounts, emergencies where agent locations matter.

    The one situation where Western Union makes sense: your recipient needs physical cash and cannot access a bank. Otherwise the apps beat it on price nearly every time.

    Method 4: Bank wire transfers

    Your US bank can wire money to India through SWIFT. It works, but it is usually the most expensive option.

    Typical cost: $25 to $50 flat wire fee, plus a 2% to 4% exchange rate markup, plus possible intermediary bank fees. (Verify with your bank.)
    Typical speed: 1 to 5 business days.
    Best for: Very large transfers where you have negotiated a rate with your bank, or employer-mandated banking channels.

    For a $1,000 transfer, a bank wire can easily cost $50 to $70 all-in. The same transfer through Wise typically costs under $15. Banks are convenient because the money never leaves your banking app, but you pay heavily for that convenience.

    Method 5: UPI, Google Pay, PhonePe, and Paytm delivery

    Many recipients prefer money directly to UPI-linked accounts, and several transfer services now support UPI delivery.

    (Verify which services and limits; this changes frequently.)

    The NRI lens: NRE vs NRO, the decision that matters more than the app

    NRE (Non-Resident External) account: For money you earn abroad. Interest is tax-free in India. Funds are fully repatriable, no limits, no special paperwork. This is where your US salary transfers should land.

    NRO (Non-Resident Ordinary) account: For India-source income: rent from your flat, dividends, sale proceeds. Interest is taxable in India (30% TDS). Repatriation is capped at $1 million per financial year and requires a CA certificate (Form 15CB) plus your declaration (Form 15CA) for every transfer.

    NRE account NRO account
    Source of funds Foreign earnings remitted to India India-source income (rent, dividends, sale proceeds)
    Tax on interest (India) Exempt Taxable, 30% TDS
    Repatriation to US Unlimited, no special paperwork Up to $1M/year, needs 15CA + 15CB
    Joint holder Another NRI only NRI or resident Indian
    Use it for Savings, NRE FDs, future repatriation Indian expenses, rent collection, local income

    The provocation: most NRIs spend an hour comparing transfer apps to save $5, then park $50,000 in the wrong account type and lose $1,500 a year in tax they did not owe. The account decision dwarfs the app decision. Get the account right first.

    Common trap: keeping your old resident savings account after becoming NRI. Under FEMA, you must convert it to NRO. Banks do enforce this, and the penalties for non-compliance are real.

    The India lens: what the recipient side looks like

    For family receiving support, the mechanics are simple: money arrives in their resident account, they spend it. Gifts from close relatives are exempt from tax in India under Section 56 of the Income Tax Act, so your parents owe nothing on what you send.

    What the recipient’s bank sees: regular monthly transfers for family support are the most normal pattern in Indian banking. Irregular large lumps draw more questions. If you are funding something big (property down payment, wedding), a quick heads-up to the recipient helps them answer the bank’s routine source-of-funds query without stress.

    The bridge: tax and compliance on both sides

    US side:

    • Gift tax: You can gift up to $19,000 per recipient per year (2026 annual exclusion, per IRS) with no filing. Above that, file Form 709. You owe no actual tax until you exhaust the $15 million lifetime exemption. So a $25,000 gift to your mother means paperwork, not payment.
    • FBAR: If your aggregate foreign accounts (including NRE/NRO) exceed $10,000 at any point in the year, file FinCEN Form 114. This is informational, not a tax, but penalties for skipping it are severe.
    • FATCA: Higher thresholds, filed with your tax return (Form 8938). Your Indian bank reports your accounts to the IRS anyway under the intergovernmental agreement.

    India side:

    • Gifts from relatives: Exempt under Section 56. Keep a simple record of the relationship and amounts.
    • NRE interest: Tax-free. NRO interest: 30% TDS, though DTAA (India-US Double Taxation Avoidance Agreement) may reduce the effective burden; claim treaty benefits when filing.
    • Large inward remittances: The recipient’s bank may ask for source documentation. Normal compliance. Keep your US transfer receipts.

    When to talk to a professional: amounts over $100,000 in a year, property transactions, or anything involving both countries’ tax systems at once. A blog (including this one) is not a substitute for a cross-border tax advisor.

    After the money lands: what NRIs actually do with it

    Use case Where it goes Why
    Family support Recipient’s resident account Spent as intended; simplest path
    Savings NRE fixed deposit (~7.0-7.5% for 1yr, verify current; tax-free) Best risk-free return available to NRIs; beats US savings rates
    Property fund NRE savings, accumulated Keeps purchase fully repatriable on future sale
    Indian mutual funds NRE or NRO (PIS route) Caution: PFIC rules make Indian MFs punishing for US taxpayers; research before investing
    Emergency buffer in India NRE savings Liquid, repatriable, tax-free interest

    Real scenarios

    Priya, H1B, Austin, sends $2,500/month. $1,500 to parents (their resident account, gift, no tax either side). $1,000 to her own NRE account, swept quarterly into a 1-year NRE FD. Total annual transfer cost difference between the cheapest and most expensive method: roughly $200. Total annual tax saved by using NRE instead of NRO for the savings portion: roughly $250 in avoided TDS. The account matters as much as the app.

    Rahul, F-1 student, Boston, receives $1,200/month from parents. Reverse direction. Parents send from India under the Liberalised Remittance Scheme ($250,000/year limit per person). They use their bank’s outward remittance; the student receives in a US account. Note: TCS (tax collected at source) applies on LRS remittances above thresholds for education; keep the receipts for the student’s records.

    Anita and Vikram, green card holders, Seattle, investing $60,000/year in India. They max out NRE FDs first (tax-free, repatriable), then consider Indian equities via the PIS route through NRE. They avoid Indian mutual funds entirely because of PFIC treatment on their US return, a $0-cost decision that saves thousands in tax complexity.

    How to get the best deal every time

    1. Compare the final rupee amount, not the fee. Two minutes on two apps before every transfer.
    2. Check the rate margin. Google “USD to INR” for the mid-market rate; measure each service’s distance from it.
    3. Time large transfers. For amounts over $10,000, watching the rate for a week can save more than switching services.
    4. Avoid credit cards. Cash-advance fees destroy any rate advantage.
    5. Fund with ACH when not in a hurry. Cheapest payment method on every platform.
    6. Check first-transfer promos, but evaluate the steady-state price. One cheap transfer means nothing if the next fifty are overpriced.
    7. Get the receiving account right. NRE for your own foreign earnings. This habit is worth more than all six above combined.

    Common mistakes to avoid

    • Judging by fees alone. The rate margin is usually the bigger cost.
    • Using your bank by default. Convenience is expensive here.
    • Sending to the wrong account type. NRE for foreign earnings, NRO for Indian income. Mixing them up is the costliest common error.
    • Keeping a resident account after becoming NRI. FEMA requires conversion to NRO. Non-compliance carries penalties.
    • Ignoring FBAR. $10,000 aggregate across foreign accounts triggers filing. The penalty for willful non-filing starts at $100,000.
    • Forgetting Indian bank holidays. A Friday evening US transfer may sit until Tuesday in India. Plan around both countries’ holidays.

    Frequently asked questions

    What is the cheapest way to send money from the US to India?
    Specialist apps (Wise, Remitly) using the mid-market rate or close to it. Compare the final rupee amount across two services before each transfer.

    Should I use NRE or NRO for transfers?
    NRE for money you earn abroad: tax-free interest, fully repatriable. NRO for India-source income like rent. Never park foreign salary in NRO if NRE is available.

    Do I pay tax on money sent to India?
    The transfer itself is generally not taxed in the US. Gifts to close relatives are exempt in India. US gift tax filing starts above $19,000 per recipient per year (2026); no tax owed until the $15 million lifetime exemption is used. FBAR filing applies if foreign accounts exceed $10,000 aggregate.

    How long does it take?
    Minutes (Remitly Express, Xoom) to 5 business days (bank wires, economy tiers). Most app transfers arrive within hours.

    Is it safe?
    Yes, with regulated, licensed money transmitters. Avoid any service that is not transparent about fees and rates.

    Can my parents send me money from India?
    Yes, under the Liberalised Remittance Scheme ($250,000 per person per year). TCS may apply above thresholds. This is the reverse corridor and follows different rules.

    Related guides

    Disclaimer: IndiaPay provides educational content about money transfers and NRI finance. We are not licensed financial advisors or tax professionals. Nothing here is financial or tax advice. Fees, rates, tax thresholds, and regulations change; verify current figures with the provider and consult a qualified cross-border professional for your situation. FEMA/RBI rules noted as of 2026; confirm current notifications before acting. We may earn a commission at no extra cost to you.

    Get the NRI money briefing: one email a week on rates, rules, and smart moves for Indians abroad.

    Disclosure: IndiaPay may earn a commission from links on this page.
  • Wise vs Remitly for India Transfers: The NRI’s Complete 2026 Comparison

    Wise vs Remitly for India Transfers: The NRI’s Complete 2026 Comparison

    The NRI’s dilemma: the cheapest transfer can still be the wrong transfer

    You are an H1B worker in Seattle. Every month you send $2,000 home. You have done the comparison, you know Wise usually wins on rate. But here is the question nobody’s comparison article answers: which Indian bank account should the money land in, and what happens to it after it arrives?

    The $8 you save picking the cheaper app is nothing compared to the money you lose parking it in the wrong account. Send $24,000 a year into an NRO savings account earning taxable interest when it could sit in an NRE account earning tax-free interest, and you have quietly given up hundreds of dollars. The transfer is the easy part. What happens after the money lands is where NRIs actually lose money.

    This guide compares Wise and Remitly on everything that affects your wallet: rate, fees, speed, limits, payout options. Then it goes further: which account the money should land in, the tax picture on both sides, and what to do with rupees once they are in India.

    The short answer

    For most transfers between $500 and $10,000, Wise gives you more rupees. Wise uses the real mid-market exchange rate and charges a transparent fee on top. Remitly gives you a slightly worse rate but sometimes charges no transfer fee, which can make it competitive for small transfers, especially your first one.

    The exception: Remitly frequently runs promotions for new customers, including special first-transfer rates. If you have never used Remitly, your first transfer may beat Wise. After the promo ends, Wise usually wins on total cost.

    If you only remember one thing from this article: always compare the final rupee amount, not the fee. A “$0 fee” transfer with a bad exchange rate costs you more than a $5 fee with a great rate.

    How each service works

    Wise (formerly TransferWise)

    Wise’s model is simple. They show you the mid-market rate, the same rate you see on Google when you search “USD to INR.” Then they add a clearly stated fee. What you see is what you get.

    • Exchange rate: Mid-market rate, no markup. (Verify live before transferring; corridors can change.)
    • Fee structure: A percentage of the amount plus a small fixed fee, varying by payment method. Bank transfer (ACH) is cheapest; debit card costs more.
    • Speed: Most USD to INR transfers arrive within hours, often the same day.
    • Limits: High limits suitable for large transfers. Check current per-transfer caps in the app before large sends.
    • Payout: Direct to Indian bank accounts, including NRE and NRO accounts. UPI support varies; verify in-app.

    Try Wise

    Remitly

    Remitly works more like a traditional remittance company with a modern app. They make money primarily on the exchange rate margin, and they offer two speed tiers.

    • Exchange rate: Below the mid-market rate. The margin varies and is wider on the slower Economy tier.
    • Fee structure: Two tiers. Express (fast, arrives in minutes) carries a fee. Economy (slower, 3 to 5 business days) often has no fee or a very small one.
    • Speed: Express: minutes. Economy: 3 to 5 business days.
    • Limits: New customers start with lower limits that increase over time and with verification.
    • Payout: Bank deposit, UPI, and cash pickup at partner locations in India.

    Try Remitly

    Head-to-head: the numbers that matter

    The only number that matters is how many rupees land in the recipient’s account for your dollar amount. Everything else is a distraction.

    Example: sending $1,000

    Walk through this calculation yourself with live numbers before every transfer:

    1. Enter $1,000 on Wise. Note the fee and the final INR amount.
    2. Enter $1,000 on Remitly (both Express and Economy). Note the fee and the final INR amount.
    3. Compare the three INR figures. The highest one wins.

    Typical pattern at this amount: Wise delivers more INR because the mid-market rate advantage outweighs its fee. Remitly Economy can come close when it charges no fee, but the wider rate margin usually still leaves it behind. Remitly Express is the most expensive of the three. (Verify live before you send; this pattern holds in most months.)

    Example: sending $5,000

    At larger amounts, the exchange rate margin matters more than the flat fee. This is where Wise’s mid-market rate pulls ahead, because Remitly’s rate margin applies to the full amount. On $5,000, even a 0.5% rate difference is $25, which dwarfs most fee differences.

    Example: sending $200

    For small transfers, the math gets closer. Remitly’s Economy tier with no fee can be competitive here, and first-transfer promotions can flip the result entirely. At this size, also consider: is it worth optimizing at all? The difference between the best and worst option on $200 is often under $3.

    Fee comparison table

    Wise Remitly Express Remitly Economy
    Exchange rate Mid-market Below mid-market Below mid-market (wider margin)
    Transfer fee Percentage + small fixed fee (verify current) Fee applies (verify current) Often $0
    Speed Hours, often same day Minutes 3 to 5 business days
    Payout options Bank deposit (NRE/NRO) Bank, UPI, cash pickup Bank, UPI, cash pickup
    Best for $500+ transfers Urgent transfers Small, non-urgent transfers

    The NRI lens: where should the money actually land?

    This is the section other comparisons skip, and it matters more than the fee difference.

    If you are sending to yourself (your own Indian accounts): send to your NRE account, not NRO. NRE accounts hold foreign-source income, the interest is tax-free in India, and the money is fully repatriable, meaning you can move it back to the US without limits or paperwork. NRO accounts are for India-source income (rent, dividends). Parking foreign salary in NRO means taxable interest and a $1 million annual repatriation cap with CA-certified paperwork (Forms 15CA/15CB) to get it back out.

    If you are sending to family: it lands in their resident Indian account. That is normal and fine. Gifts to close relatives are exempt from gift tax in India under Section 56 of the Income Tax Act. On the US side, you can gift up to $19,000 per recipient per year (2026 annual exclusion, per IRS) without filing a gift tax return. Above that, you file Form 709, but you owe no tax until you exhaust the $15 million lifetime exemption.

    The provocation most NRIs miss: the transfer app is a commodity. The account the money lands in is the strategy. An NRI who sends $2,000/month via the cheapest app into an NRO account, then pays 30% TDS on the interest and cannot easily repatriate, has lost more than any fee comparison will ever show.

    The India lens: what the recipient experiences

    Your parents in Pune do not care about mid-market rates. They care that the money arrives, that the SMS from the bank comes through, and that nobody calls them asking questions.

    Transfers to family for support are routine and unrestricted in practice. The recipient’s bank may ask about source and purpose for large or unusual transfers; this is normal compliance, not suspicion. What helps: consistent amounts on a regular schedule look cleaner than irregular large lumps.

    If your family does not have easy bank access, Remitly’s cash pickup at partner locations is a genuine advantage Wise does not match. For everyone with a bank account, direct deposit is faster and safer on both platforms.

    The bridge: after the money lands in India

    Money that just sits in an Indian savings account earning 3.5% while inflation runs higher is quietly shrinking. Here is what NRIs typically do with transferred funds, in order of commonality:

    • NRE fixed deposits: 1-year NRE FD rates run around 7.0 to 7.5% (verify current), interest tax-free in India. This is the default parking spot for NRI savings and the reason the NRE account matters so much.
    • Family support: Spent as intended. No optimization needed, but keep records.
    • Indian mutual funds: NRIs can invest via NRE/NRO, but note the US tax sting: Indian mutual funds are PFICs for US taxpayers, with punishing tax treatment. This deserves its own guide (coming in our investing pillar).
    • Property: Many NRIs fund Indian property purchases through accumulated NRE balances. Fully repatriable on sale (within overall limits), unlike NRO-funded purchases.

    Speed: when minutes actually matter

    If the money needs to arrive today, your options are Wise (usually same day for USD-INR) or Remitly Express (minutes). Remitly Economy takes several business days, which makes it a poor choice for anything time sensitive.

    One thing people miss: “minutes” versus “hours” rarely matters in practice. If your family does not need the money this exact hour, paying extra for Express is usually wasted money. Medical emergency at 2 AM? Express. Monthly support? Economy or Wise.

    Limits and verification

    Both services require identity verification and raise your limits as you verify further. If you regularly send large amounts (funding an NRE account, paying a property installment), complete full verification before you need it and check per-transfer caps in the app. Hitting a limit mid-transfer is frustrating and avoidable.

    Trust and safety

    Both are established, regulated US money transmitters (Wise is publicly traded; Remitly trades on NASDAQ as RELY). Neither is going to disappear with your money. Not a differentiator between them. But people rightfully ask.

    Our honest verdict for 2026

    • Sending $500 or more? Use Wise. The mid-market rate beats Remitly’s margin in almost every case.
    • Sending under $500 and not in a hurry? Check Remitly Economy. Sometimes cheaper, sometimes not. Compare the final INR both times.
    • First transfer ever? Check Remitly’s new-customer promotion. The promo rate can beat everything, but only once.
    • Need it in minutes? Remitly Express is fastest, but you pay for speed. Wise is usually fast enough.
    • Sending to yourself? Use Wise into your NRE account. Then put it in an NRE FD. The account choice matters more than the app choice.

    The habit that saves you the most money over time: check both apps before every transfer, and check which account receives it. Rates change monthly. The winner last month is not guaranteed to win this month. Sixty seconds, highest-value habit in this guide.

    The fine print nobody reads

    • Rates move: Every figure in this article should be re-verified live before you transfer. We update at publish time; the market updates every minute.
    • First-transfer promos expire: Do not pick a long-term provider based on a one-time promo rate.
    • NRO trap: Do not accumulate foreign earnings in NRO. The 30% TDS on interest and the repatriation paperwork will cost you more than any transfer fee you saved.
    • Large transfers and questions: Amounts over $10,000 have US reporting implications, and the recipient’s Indian bank may ask about source. Keep records. This is routine.
    • FEMA compliance: You cannot hold a regular resident savings account once you are an NRI; convert to NRO. Depositing foreign income into NRO when NRE is available is not illegal, but it is financially wasteful.

    Frequently asked questions

    Is Wise better than Remitly for India?
    For most transfer amounts, yes. Wise’s mid-market exchange rate usually delivers more rupees. Exceptions: small transfers on Remitly Economy and first-transfer promotions.

    Should I send to NRE or NRO?
    NRE for money you earn abroad. It is tax-free and fully repatriable. NRO is for India-source income like rent. Sending foreign salary to NRO is the most common NRI money mistake.

    Do I pay tax on money sent to India?
    The transfer itself is generally not taxed in the US. Gifts to close relatives are exempt in India. US gift tax filing (Form 709) kicks in above $19,000 per recipient per year (2026), but no tax is owed until the $15 million lifetime exemption is exhausted. Consult a professional for large amounts.

    Does Remitly have hidden fees?
    Not hidden, but the cost sits in the exchange rate rather than a stated fee. Always compare the final rupee amount, not the advertised fee.

    Which is faster?
    Remitly Express (minutes) is the fastest single option. Wise typically completes USD-INR within hours. Remitly Economy takes 3 to 5 business days.

    Related guides

    Disclaimer: IndiaPay provides educational content about money transfers and NRI finance. We are not licensed financial advisors or tax professionals. Nothing here is financial or tax advice. Fees, rates, and regulations change; verify current figures with the provider and consult a qualified professional for your situation. We may earn a commission at no extra cost to you.

    Get the NRI money briefing: one email a week on rates, rules, and smart moves for Indians abroad.

    Disclosure: IndiaPay may earn a commission from links on this page.