The Three-Week Wait
In 1994, if you lived in New Jersey and wanted to send $500 to your parents in Kochi, here is what you did:
You went to your bank. You filled out a paper form. You paid a fee that nobody could quite explain. The bank issued a demand draft, a physical piece of paper promising payment, which you mailed to India by international post. Your parents received it in two to three weeks, took it to their bank, and waited another week for it to clear.
Total elapsed time: roughly a month. Total cost: somewhere between 5% and 10% once you added up the fees, the terrible exchange rate, and the postage. Total transparency: zero. For most of that month, your $500 existed only as a rumor.
This was not the backward option. This was the normal option.
The Menu of Bad Options
The 1990s NRI had roughly four ways to move money, and each was bad in its own special way:
| Method | How it worked | Speed | Cost | The catch |
|---|---|---|---|---|
| Demand draft | Bank-issued paper draft, mailed internationally | 3-5 weeks door to door | 5-10% all-in | Could be lost, stolen, or delayed by the postal service of two countries |
| Telegraphic transfer (TT) | Bank-to-bank wire via SWIFT/telex | 3-7 days | $25-45 flat fee + 2-4% rate markup | Only worth it for large amounts; paperwork at both ends |
| Carried cash | The uncle with dollars in his socks | Next flight home | 0% (plus risk) | Customs limits, theft risk, and the exchange happened at whatever rate the local money changer offered |
| Hawala | Trust-based informal network | Hours to days | 1-2% | Illegal in most jurisdictions; no recourse if the operator vanished |
Read that table again. The illegal option was the fastest and cheapest. That tells you everything about how badly the formal system served migrants in the 1990s.
Why It Was So Bad: The 1991 Context
To understand 1990s remittances, you have to understand 1991. India went through a balance-of-payments crisis so severe that the government airlifted 67 tonnes of gold to London as collateral for emergency loans. Foreign exchange reserves had fallen to roughly $1 billion, barely three weeks of imports.
The reforms that followed gradually opened the capital account and made the rupee more flexible after 1993, but the plumbing of cross-border money movement stayed Victorian for another decade. As recently as 2003, 86% of all non-cash payments in India were still paper instruments: cheques, demand drafts, cash. Electronic payments were a rounding error.
In 1990, India received just $2.38 billion in remittances and ranked 8th in the world. By 1995, it was number one at $6.2 billion. By 2000: $12.9 billion. By 2010: $53.5 billion. In FY25: $135.4 billion. The World Bank data shows India has topped the global remittance table for 23 of the 27 years since 1995.
The money did not just grow. The pipes changed completely.
The NRI Lens: What It Felt Like
Ask any NRI who moved abroad before 2000, and the remittance stories come out like war stories.
There is the story of the demand draft that arrived after the medical emergency it was meant to cover. The story of the telegraphic transfer where the bank “lost” the SWIFT message for eleven days. The story of timing a trip home around carrying the maximum legal cash, and the specific anxiety of the customs line at Mumbai airport.
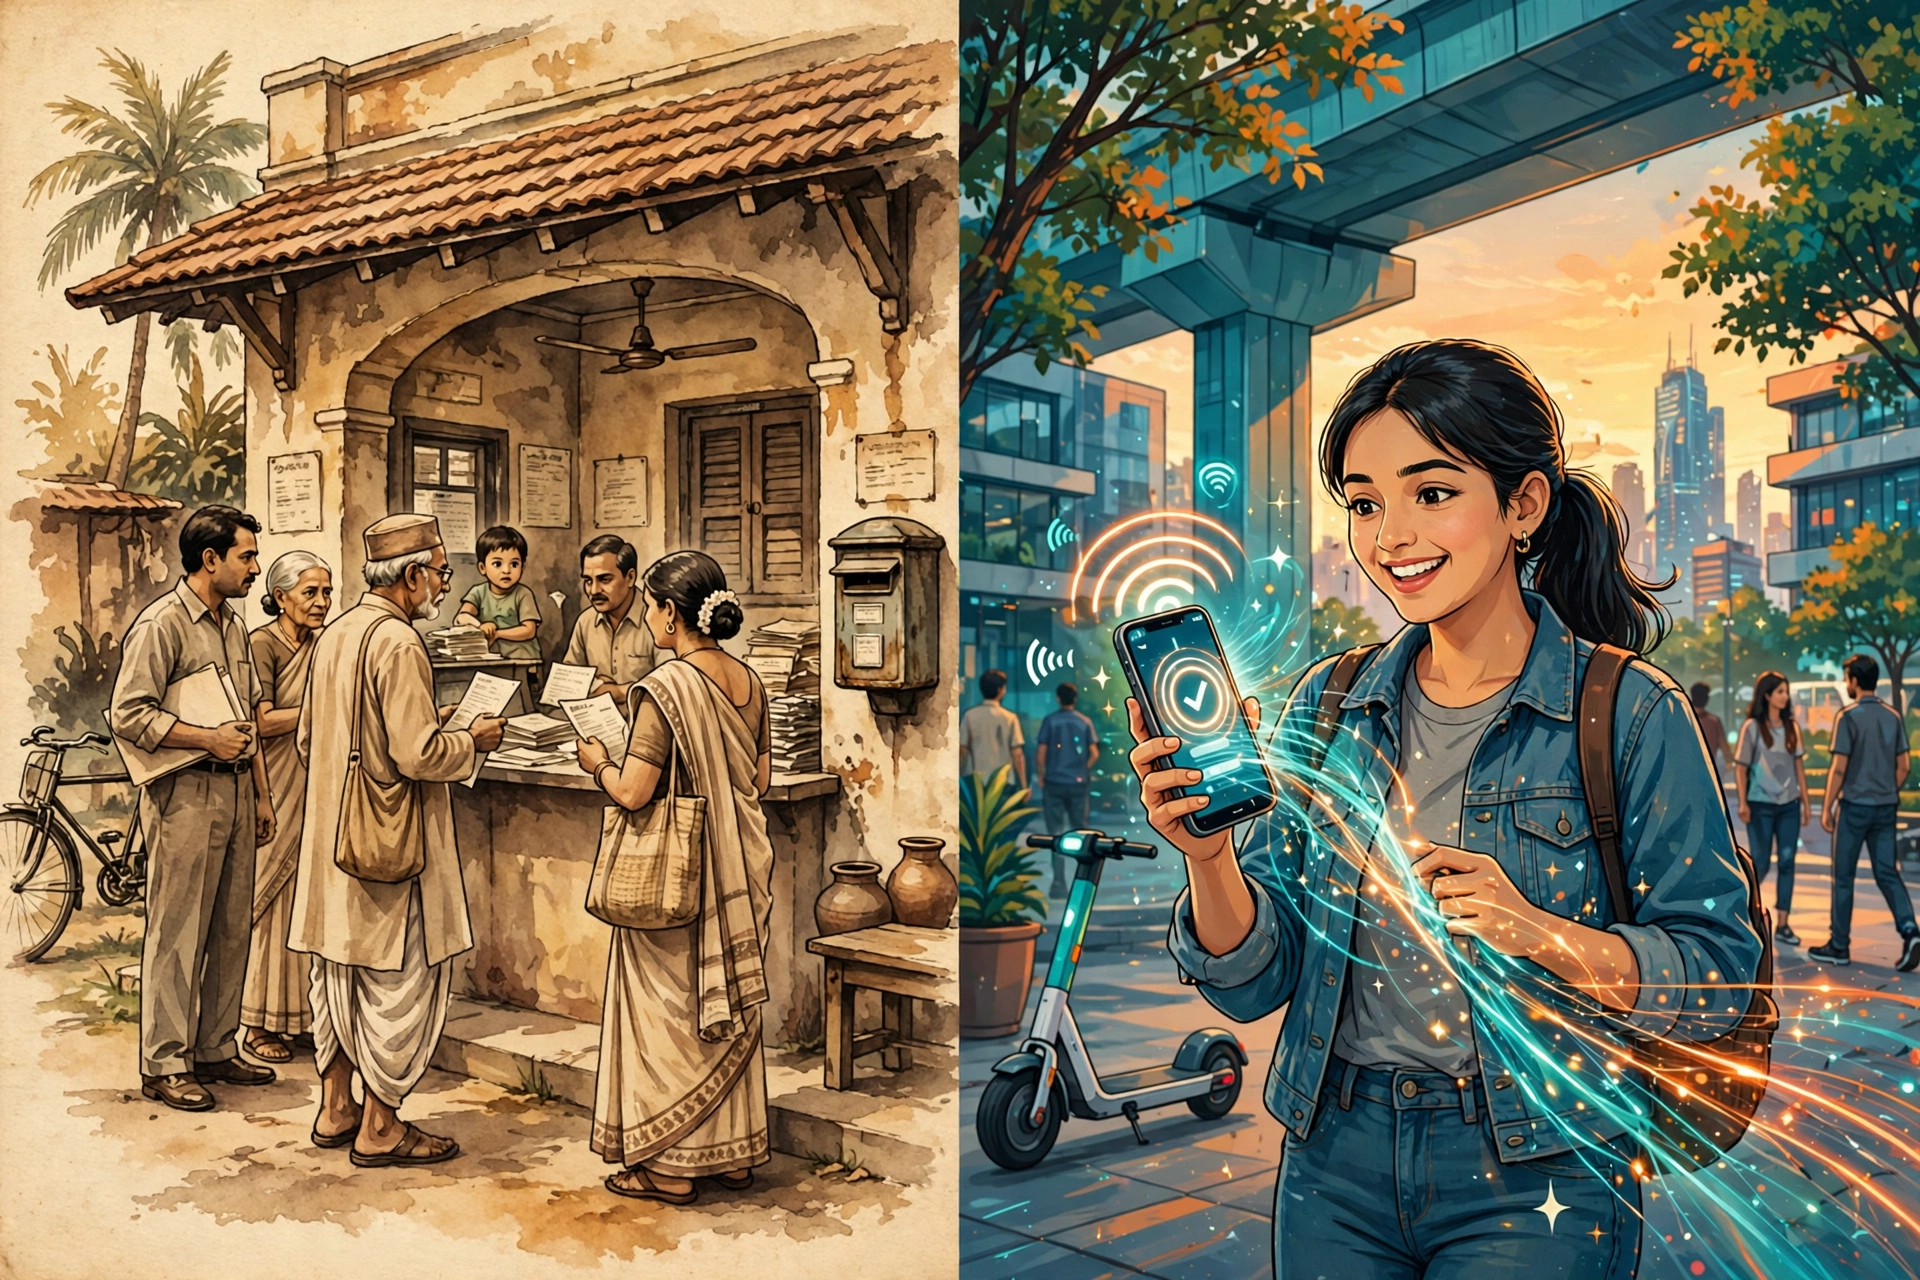
But there is also something the old-timers describe that the app generation does not have: the ritual weight of it. Sending money in 1995 was an event. You went to the bank. You stood in line. You filled out forms in triplicate. You called home to say “I sent it, it should reach by the end of the month.” The slowness created a ceremony around the act. Today’s instant transfer is efficient, but nobody calls home to announce a Wise transfer the way they announced a demand draft.
Speed ate the ritual. Whether that is a loss or a liberation depends on how old you are.
The India Lens: What the Family Experienced
From the receiving side, the 1990s system had a peculiar feature: the delay was a budgeting tool. Families knew the money was coming “sometime next month,” and planned around the uncertainty. The arrival of the draft was an occasion. Neighbors knew. The bank manager knew.
Compare that to today, when $500 lands via IMPS in four minutes and nobody marks the occasion. The emotional bandwidth of remittances has collapsed even as the financial bandwidth exploded. Your parents in 1995 felt each transfer. Your parents in 2026 get a push notification.
The old system’s slowness also protected people from themselves. You could not panic-send money at 2 AM because the rupee moved. You could not check the rate twelve times a day. The friction was a feature, accidentally.
The Great Inversion
Now, the reframe on today’s fees:
The global average cost of sending remittances is 6.36% (World Bank, Q3 2025), still more than double the UN’s 3% target. Banks charge nearly 15%. The fintech apps charge 1% or less. NRIs complain, rightly, that even 1% is too much.
But the 1990s NRI paid 5 to 10% and waited a month. The hawala user paid 1 to 2% and broke the law. Today’s “expensive” legal option is cheaper than the 1990s illegal option, and it arrives in minutes.
The real revolution was not speed. It was legitimacy at low cost. For the first time in history, an ordinary migrant can move money across the world cheaply, quickly, and entirely within the law. Every generation before this one had to choose two of the three.
The Thought Provocation
Nostalgia for the demand-draft era is misplaced, but it contains a real insight: friction made money meaningful. The month-long wait, the trip to the bank, the phone call announcing “I sent it”, these turned a financial transaction into an act of care with weight and ceremony.
Today’s system optimized away the wait, the cost, and the ceremony all at once. The money moves perfectly. But something was lost when sending $2,000 home became no more momentous than ordering groceries. The apps solved the economics of remittances completely, and accidentally deleted the meaning of remittances.
Maybe the next revolution in money movement will not be about making it faster or cheaper. Maybe it will be about making it matter again. The uncle with cash in his socks was inefficient, risky, and illegal. He was also, in some way the apps have not figured out, present.
The NRI money playbook, one email a week
Remittance tricks, NRE/NRO guides, tax deadlines, and investment rules for Indians abroad. Practical, numbers-first, no fluff.
Financial disclaimer: This is a historical and educational piece, not financial advice. Sources: World Bank remittance data via The Hindu BusinessLine analysis (1990-2021 rankings); RBI payment system data (86% paper instruments in 2003); World Bank Q3 2025 remittance cost data (6.36% global average); Economic Survey of India 2025-26.